All Categories
Featured
Choosing the Best 2026 Medicare Advantage Plans
Table of Contents
Term life insurance is normally better for the majority of people due to its lower premiums and simple protection. Whole life insurance uses lifelong protection and a cash worth component but is more costly.
The cost of term life insurance for a 50-year-old varies based on health and coverage quantity. Typically, a $250,000 20-year term policy for a healthy 50-year-old woman might cost around $26.42 monthly.
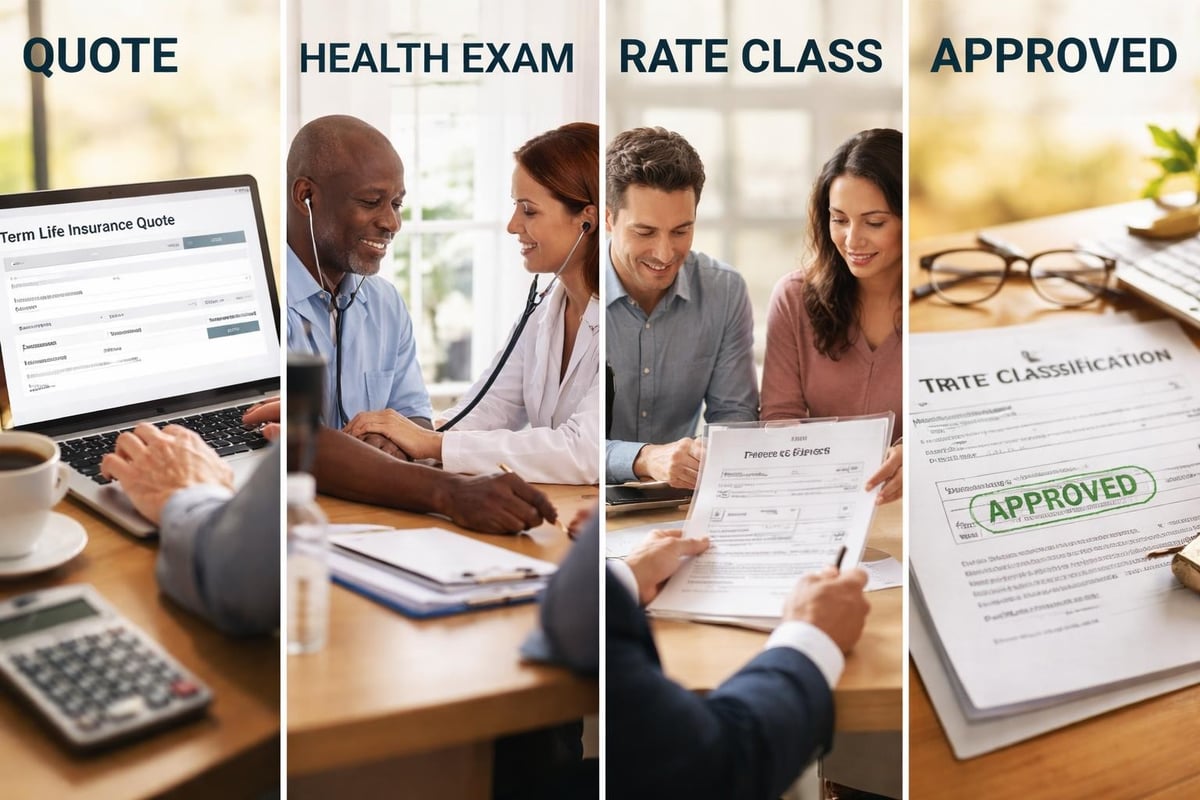
Image credit: Keating Multiple kinds of life insurance policies fall under the umbrella of term life insurance. In order to pick the ideal insurance plan, it assists to become more knowledgeable about the various sort of term life insurance prices quote that are readily available to customers. Level term life insurance policies include insurance premiums that are guaranteed to remain the same during the entire length of the insurance term.
2026 Term Life Insurance Rates in the US
You can also look for level term life insurance quotes that last for just five, 10 or 15 years. Some level term life insurance coverage plans featured sustainable terms. Once the initial term ends, you can have your insurance policy renewed with the understanding that your premiums will increase on a yearly basis.
Some yearly renewable term life policies are reducing term life policies, indicating that the premiums do not change throughout the life of the insurance coverage however the death benefit shrinks with time. In many cases, people with term life insurance coverage don't receive any cash back if they outlive their insurance coverage.
When you buy return of premium term life insurance coverage, you'll get a complete refund for all of the premiums you pay for many years if you're still alive when your insurance coverage term ends. As you compare life insurance products, you might also discover home mortgage term life insurance coverage quotes. Home loan term life insurance coverage makes your mortgage lending institution instead of your liked ones your recipient.
Referred to as much as possible about the types of term life policies that insurance coverage business use is essential when you're attempting to meet your short- and long-lasting monetary goals. As you evaluate term life insurance coverage quotes, you'll need to find out how much life insurance coverage you need. That suggests you'll have decide the length of time you desire your insurance coverage to last and identify how much insurance protection suffices.
At stated value, they can vary anywhere from $25,000 to $5 million. Typically, the greater the protection amount and the longer the insurance term, the more costly the insurance plan will be. The coverage quantity you pick when buying a term life policy (and whether you pay your premiums) impacts the benefit quantity that will be paid out to your beneficiaries following your death.
Securing Financial Security with Whole Life Insurance
The quantity of life insurance coverage you require will depend upon the amount of debt you're bring, your income and whether you have savings and investments. If your partner works, you may not need as much life insurance coverage as you would if your hubby or partner wasn't working at all.
Bottom line: Your life insurance coverage requires can change throughout your lifetime. If you purchase a home or handle multiple home improvement tasks, it might be an excellent idea to have adequate insurance to cover your mortgage and any restorations you have actually made in case of your unfortunate death.
Many insurance business and sites use complimentary term life insurance estimates online. In minutes, you can get a price quote of what a life insurance coverage policy would cost you. Life insurance prices quote often inform you which ranking class you fall under. People who qualify for the best insurance rates will fall into the incredibly favored, select or preferred categories.
In order to get an insurance coverage quote, you'll need to offer specific details about yourself. Be prepared to enter your zip code, address, date of birth, gender, height and weight. You'll likely have to respond to concerns about your health status and your individual habits (consisting of whether you're a smoker).
Evaluating Indexed Universal Life Benefits for Retirement
An insurance provider will desire to know as much as possible about you and the type of way of life you live. That's because when a guaranteed person passes away, the insurer needs to pay up. To reduce the threat of needing to pay advantages, an insurer can make term life insurance protection more pricey for people who live risky lives.
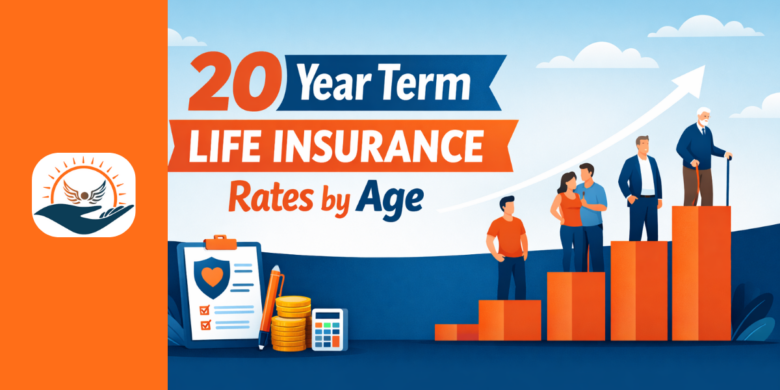
By buying life insurance at a younger age, your premiums will likely be more affordable. A 20-year term life policy would cost a 30-year-old female non-smoker as low as $213 each year. On the other hand, the average 45-year-old female non-smoker would pay $496 per year for a 20-year term life insurance coverage policy from the very same company.

Latest Posts

Projecting 2026 Term Life Insurance Rates and Value
Evaluating PPO and HMO Insurance
Indexed Universal Life Benefits for Security